Guide
Payslip Deductions Explained (2026/27): PAYE, NI, Pension & Student Loan
Most payslip deductions fall into five buckets: tax, National Insurance, pension, student loan, and salary sacrifice.
Quick answer
If you can identify which line changed, you can usually work out why the net pay changed.
On this page
Example 07
Weekly pay with overtime
Hourly contract · England · Tax week 1 · 2026/27
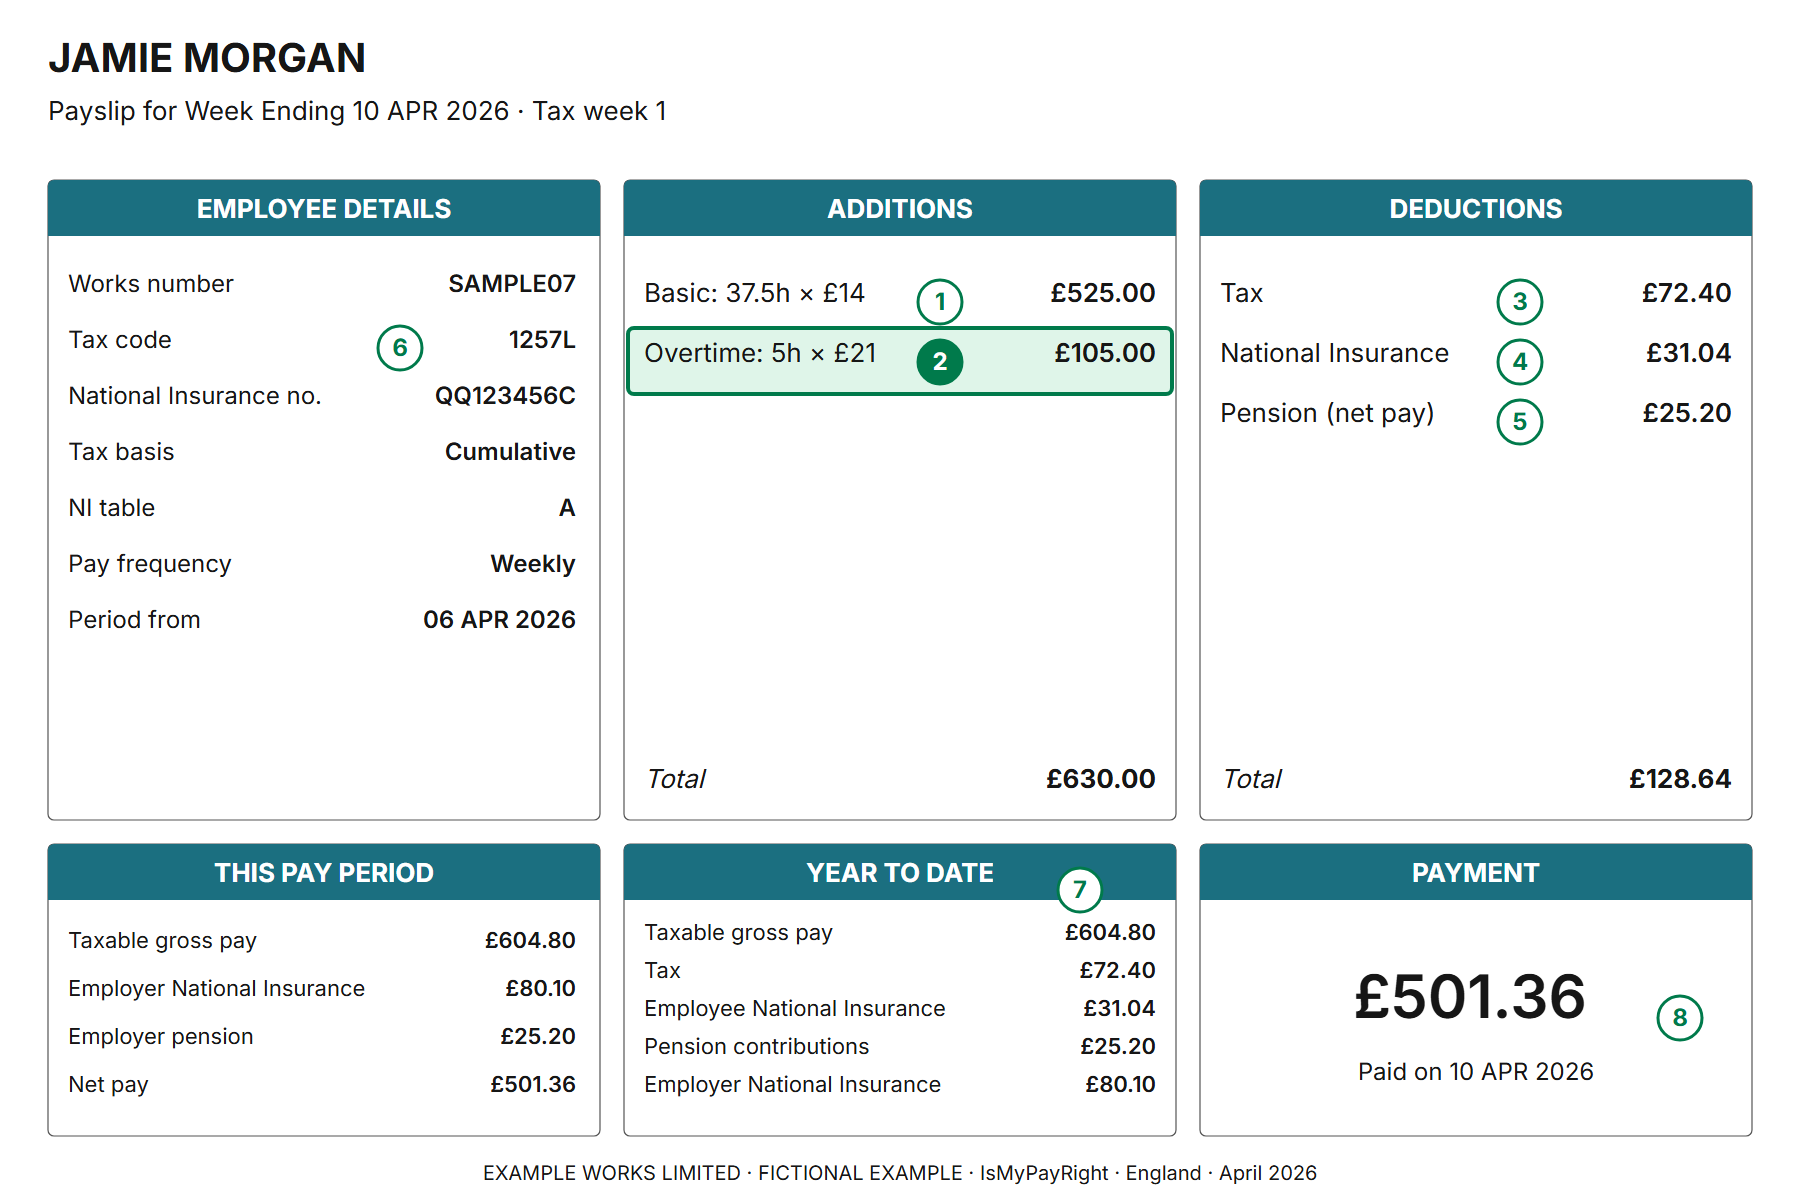
Illustrative BrightPay-style weekly layout
Fictional employee and employer. Based on BrightPay’s published UK templates; this example uses weekly pay. Use the numbered explanation buttons, or enlarge the payslip to select a line on the document.
Line 2 of 8
Overtime hours and rate
5 × £21 = £105.00
Five overtime hours are paid at £21, the 1.5 times rate agreed in this example contract. Total hours are 42.5 and gross pay is £630.
On your own payslip
Check the hours approved, the agreed overtime rate and the payroll cut-off. An overtime premium depends on the contract.
Read all 8 explanations
1. Basic hours and rate
37.5 × £14 = £525.00
Basic pay records 37.5 hours at the contract’s £14 hourly rate. This is weekly pay, not a monthly salary divided into four.
Match paid hours to your time record and the rate to your contract. Check whether breaks are paid.
2. Overtime hours and rate
5 × £21 = £105.00
Five overtime hours are paid at £21, the 1.5 times rate agreed in this example contract. Total hours are 42.5 and gross pay is £630.
Check the hours approved, the agreed overtime rate and the payroll cut-off. An overtime premium depends on the contract.
3. PAYE Income Tax
£72.40
The pension leaves £604.80 taxable pay. After £241.92 week-one free pay, £362.88 is rounded down to £362 and taxed at 20%.
Use weekly PAYE and the full tax code. Monthly free pay would give a different result.
4. Weekly National Insurance
£31.04
Category A employee NI is 8% of £630 minus the £242 weekly threshold. The ordinary pension contribution does not reduce NI earnings.
Check the NI category and pay frequency. Annual salary alone cannot reconstruct an irregular weekly NI deduction.
5. Pension on basic and overtime pay
£25.20
This net-pay scheme takes 4% of all £630 gross, including overtime. The employer separately pays another £25.20.
Ask which earnings your pension scheme includes. A qualifying-earnings scheme or a different contribution agreement would change the amount.
6. Tax code and pay frequency
1257L · weekly · week 1
This is cumulative code 1257L in the first tax week of 2026/27. There is no earlier pay or tax to bring into the calculation.
Read the code, basis, frequency and tax week together. A W1 instruction later in the year would ignore earlier weeks.
7. Year-to-date totals
First tax-week totals
The year-to-date figures equal this period’s figures because it is the first payment of the tax year in this employment.
Later payslips should carry earlier totals forward. Compare like-for-like totals within the same employment and tax year.
8. Net pay
£501.36
£630 gross minus £25.20 pension, £72.40 tax and £31.04 NI leaves £501.36 for the employee.
Match this amount to the bank payment. Employer NI and employer pension are separate costs.
Example assumptions, calculations and sources
Follow the money
From £630.00 to £501.36
Employee deductions account for the £128.64 difference. Employer contributions are paid separately and do not come off this take-home amount.
| Item | Amount |
|---|---|
| Gross pay | £630.00 |
| PAYE Income Tax | -£72.40 |
| Employee National Insurance | -£31.04 |
| Employee pension | -£25.20 |
| Net pay | £501.36 |
The example’s assumptions
- England taxpayer, aged 30, one employment, weekly pay, cumulative 1257L and NI category A.
- Tax week 1 of 2026/27; 6–10 April period, paid on 10 April. No earlier tax-year pay or tax.
- Defined contract: 37.5 basic hours at £14 and five approved overtime hours at £21. The 1.5 times overtime rate is a contract term, not a universal entitlement.
- Net-pay pension scheme: 4% employee and 4% employer on all gross pay, including overtime.
- No loans, salary sacrifice, taxable benefits, other income or deductions. No holiday pay is rolled into these rates.
See the calculation method
Basic pay is 37.5 × £14 = £525. Overtime is 5 × £21 = £105. Total paid hours are 42.5 and gross pay is £630.
Employee pension is £630 × 4% = £25.20. Employer pension is another £25.20, paid separately. Taxable pay is £604.80; NI earnings remain £630.
HMRC v24 week-one free pay for 1257L is £241.92. £604.80 − £241.92 = £362.88; round down to £362 and multiply by 20%: £72.40 PAYE.
Employee NI is (£630 − £242) × 8% = £31.04. Employer NI is (£630 − £96) × 15% = £80.10, not an employee deduction.
Net pay is £630 − £25.20 − £72.40 − £31.04 = £501.36. These weekly thresholds must not be replaced by monthly or annual thresholds.
These are independently worked fictional illustrations using published rules and the stated contract assumptions. Actual payroll can depend on earlier pay, the employer’s settings and rounding method.
Sources for the layout and figures
- Payslips and variable hours
Acas
Show the hours behind pay that varies with time worked. Scope: Great Britain.
- Printing payslips: BrightPay A5 and A4 templates
BrightPay UK
Published visual references for the employee, additions, deductions and payment panels.
- What you and your employer pay into a workplace pension
GOV.UK
Scheme rules decide the earnings basis; employers can pay more so the employee contributes less.
- Payroll technical specifications: Income Tax
HMRC
Version 24.0: weekly and monthly code allowances, non-cumulative tax and PAYE rounding.
- Rates and thresholds for employers 2026 to 2027
HMRC
Category A weekly and monthly employee and employer NI rates and thresholds.
- Employer further guide to PAYE and National Insurance contributions
HMRC
Net pay pension contributions reduce PAYE pay without reducing NI earnings.
Gross pay vs taxable pay vs NI-able pay
Your payslip may show several different pay figures, and understanding which one each deduction is based on is essential for checking whether the numbers are correct.
Gross pay is the total amount you are contractually entitled to for the pay period before any deductions. It includes your base salary, overtime, commission, bonuses, and any statutory payments such as SSP or SMP. Gross pay is the starting point for everything else.
Taxable pay is the pay on which payroll calculates income tax. Pension contributions under a net pay arrangement reduce it; relief-at-source pension deductions do not. Pension salary sacrifice reduces contractual cash pay, so payslips may show gross pay already reduced by the sacrifice. Do not subtract it twice. Taxable benefits can also affect the figure.
NI-able pay is the earnings on which National Insurance is calculated. Ordinary employee pension contributions under either net pay or relief at source do not reduce it. Pension salary sacrifice generally reduces both taxable cash pay and NI-able pay. Your payslip layout may show these adjustments differently.
A simple example: suppose one employer pays you £2,000 gross in a month and deducts a £100 employee pension under a net pay arrangement, with no other pay or adjustments. These are illustrative pay figures, not a tax calculation or a standard pension contribution.
| Figure for this month | Amount | Why |
|---|---|---|
| Gross pay | £2,000 | Pay before the employee pension and other deductions |
| Taxable pay | £1,900 | £2,000 less the £100 net pay pension |
| NI-able pay | £2,000 | An ordinary employee pension contribution does not reduce earnings for NI |
HMRC’s pension contribution rules explain this difference. The £1,900 is used for Income Tax; it is not your take-home pay. A relief-at-source pension or pension salary sacrifice would need a different comparison. Check the arrangement with payroll rather than subtracting every pension line from both pay figures.
See the lines on an example payslip
Explore a fictional payslip, follow its deductions and check how the gross and net figures fit together.
PAYE income tax
PAYE (Pay As You Earn) is the mechanism through which income tax is collected via payroll. Your employer deducts the estimated tax due each pay period and pays it directly to HMRC on your behalf.
The income tax bands for England, Wales, and Northern Ireland in 2026–27 are:
| Band | Income range | Rate |
|---|---|---|
| Personal allowance | Up to £12,570 | 0% |
| Basic rate | £12,571 – £50,270 | 20% |
| Higher rate | £50,271 – £125,140 | 40% |
| Additional rate | Above £125,140 | 45% |
Scotland has a separate set of income tax bands set by the Scottish Parliament. Scottish taxpayers have a six-band structure with a starter rate of 19%, basic rate 20%, intermediate rate 21%, higher rate 42%, advanced rate 45%, and top rate 48% on income above £125,140. The codes for Scottish taxpayers begin with the letter S (e.g. S1257L).
The personal allowance tapers by £1 for every £2 of adjusted net income above £100,000, reaching zero at £125,140. For employment income in England, Wales and Northern Ireland, that can produce an effective 60% income-tax rate within the taper range. Scotland differs; NI and student loans are separate deductions.
Cross-check the deduction type
If the line on the payslip could be salary sacrifice or another tax-sensitive deduction, these pages help you narrow it down before contacting payroll.
National Insurance
For most employees, National Insurance is calculated separately for each pay period rather than cumulatively like PAYE. Directors have annual earnings rules, and errors or overpayments can still be corrected. A bonus therefore needs checking against that period’s NI thresholds, not simply one twelfth of annual thresholds.
Employee NI rates for category A in 2026–27: other category letters can have different rates.
| Weekly earnings | Monthly earnings | Employee NI rate |
|---|---|---|
| Up to £242 | Up to £1,048 | 0% |
| Above £242 up to £967 | Above £1,048 up to £4,189 | 8% |
| Above £967 | Above £4,189 | 2% |
Employer NI is a separate cost borne by the employer, not deducted from your pay, at 15% on earnings above the secondary threshold of £96 per week (£5,000 per year) from April 2025. Employer NI does not appear on your payslip as a deduction from your wages, but it is visible to your employer as a payroll cost — which is why salary sacrifice arrangements (which reduce employer NI as well as employee NI) are attractive to both parties.
The table uses the thresholds for the actual pay frequency. NI categories, earnings periods and the treatment of specific payments matter; do not assume that the income-tax calculation also checks NI.
Working through an umbrella? Its assignment income can fund employer costs before your employee gross pay is established. This differs from deducting employer NI from your gross wages. Use the umbrella payslip and assignment-rate checks to separate the reconciliation statement from employee deductions.
Workplace pension
Workplace pension contributions are one of the most valuable deductions on a payslip, even though they reduce take-home pay. Under auto-enrolment legislation, both you and your employer must contribute to a qualifying pension scheme.
2026–27 minimum contributions on qualifying earnings:
- Usual employee contribution: 5% of qualifying earnings, including tax relief where applicable
- Employer minimum: 3% of qualifying earnings
- Qualifying earnings band: £6,240 – £50,270 per year
The usual minimum total is 8%, including at least 3% from the employer. If the employer pays more, the employee may pay less. Check whether your scheme uses qualifying earnings or a different pay basis. At £25,000, 5% of (£25,000 − £6,240) is £938 a year, averaging £78.17 a month including any tax relief. Under relief at source, the cash deducted is lower because the provider adds basic-rate relief.
Eligible workers aged 22 to State Pension age earning above £10,000 a year are normally automatically enrolled, subject to the payroll-period assessment. Other workers aged 16 to 74 can ask to join. Employer contributions are normally required if earnings exceed £6,240 a year, even where automatic enrolment is not required; below that level, the employer does not have to contribute. See the workplace pension guide.
How the deduction appears on your payslip depends on the type of arrangement:
- Salary sacrifice pension: shown as a pre-tax deduction; reduces both taxable pay and NI-able pay.
- Net pay arrangement: deducted before income tax; reduces taxable pay but not the earnings used for NI.
- Relief at source: deducted from net pay after all tax and NI; the pension provider claims 20% tax relief from HMRC and adds it to your pot.
Student loan repayments
Student loan repayments are collected through payroll. Deductions can start from an HMRC notice or relevant P45 or starter information. Check which repayment plan you are on rather than choosing a plan by where you live now. Ask payroll or the Student Loans Company about an incorrect plan or deductions that should stop.
Repayment thresholds and rates for 2026–27:
| Plan | Annual threshold | Repayment rate above threshold |
|---|---|---|
| Plan 1 | £26,900 | 9% |
| Plan 2 | £29,385 | 9% |
| Plan 4 | £33,795 | 9% |
| Plan 5 | £25,000 | 9% |
| Postgraduate Loan | £21,000 | 6% |
Payroll uses the earnings figure used for employer Class 1 NI and the threshold for that pay period. HMRC requires deductions to be rounded down to whole pounds. On Plan 2 with £3,000 monthly earnings, (£3,000 − £2,448.75) × 9% = £49.6125, so payroll deducts £49.
If you have both an undergraduate and a postgraduate loan, both deductions appear separately on your payslip. Repayments do not reduce taxable pay or NI-able pay — they are post-tax deductions. Use the post-tax deduction examples and payroll checklist to reconcile these lines with the final bank payment.
Salary sacrifice
Salary sacrifice (also called salary exchange) means agreeing to lower cash salary in exchange for a benefit. The tax and NI treatment depends on the benefit; a reduced salary does not make every benefit tax-free. See HMRC’s salary-sacrifice guidance.
Common salary sacrifice schemes:
- Pension: if a £100 sacrifice falls entirely within the 20% income-tax and 8% employee-NI bands, the employee saves £28 (£20 + £8), making the take-home cost £72 before other effects such as student loans. A possible £15 employer-NI saving is separate and is not automatically added to your pension.
- Electric vehicle (EV) lease: a zero-emission company car has a 4% benefit-in-kind percentage in 2026–27. With a £40,000 taxable list price and a full year of availability, that gives £1,600 of taxable benefit, or £320 tax if all taxed at 20%. Compare this tax and the take-home cost of the sacrifice with the alternative lease cost.
- Cycle-to-work: qualifying bike and safety-equipment schemes can use salary sacrifice; check the scheme conditions with your employer.
- Holiday purchase: buy additional leave; confirm whether the employer uses a gross-pay reduction or another deduction arrangement.
A payslip may show a separate sacrifice line or gross cash pay already reduced. Do not subtract it twice. Taxable pay, NI-able earnings and pensionable pay can differ, especially with payrolled benefits or a protected reference salary; ask payroll which basis it uses for each deduction.
Other deductions
Beyond tax, NI, pension, and student loan, a variety of other deductions can appear on a UK payslip. Most are uncommon or situation-specific, but they can cause confusion when they appear unexpectedly.
- Debt deductions: court orders, council tax, child maintenance and DWP attachments have different rules. They reduce cash pay without reducing taxable pay. Ask payroll which authority issued the instruction, how it calculated the amount and which protected-earnings rule applies. See the debt-deduction checks.
- Trade union subscriptions: an authorised payroll deduction. Ordinary union fees are generally not tax-deductible, but HMRC describes exceptions, including qualifying professional subscriptions.
- Employee share schemes: SAYE or SIP payments may appear. SIP partnership shares can be bought from gross pay up to the lower of £1,800 or 10% of salary each tax year; keeping the tax advantages also depends on the scheme’s holding rules.
- Season ticket loans: an employer may advance travel costs and recover them through payroll. The usual small-loan tax exemption depends on the combined balance of employment-related beneficial loans staying at £10,000 or less throughout the year, not just the season ticket loan. Salary-sacrifice loan arrangements have different rules.
- Childcare vouchers (legacy schemes): new sign-ups closed in October 2018, but existing members still have voucher deductions. Basic-rate taxpayers can sacrifice up to £55 per week (£2,860/year) tax and NI free.
- Salary advances: if you have taken a salary advance through an employer scheme, the repayment appears as a deduction in subsequent months.
Worked payslip at £35,000
This illustration uses £35,000 annual salary, a monthly payment of £2,916.67 on 30 April 2026 (tax month 1), 1257L cumulative, category A NI, a Plan 2 loan and a net pay pension at 5% of qualifying earnings. Assume no earlier pay or tax in the tax year, no benefits and no other adjustments. PAYE below uses HMRC’s manual tax tables; this is a worked illustration, not a claim that every payroll method returns identical pennies.
| Item | Amount | Basis |
|---|---|---|
| Monthly gross pay | £2,916.67 | £35,000 ÷ 12 |
| Pension (net pay arrangement, 5%) | −£119.83 | 5% of (£2,916.67 − £520.00) |
| Taxable pay | £2,796.84 | Gross − pension |
| PAYE (1257L, month 1 manual tables) | −£349.60 | £1,748 whole pounds of pay after the code adjustment × 20% |
| Employee NI (category A) | −£149.49 | 8% of (£2,916.67 − £1,048), rounded to pennies |
| Student loan Plan 2 | −£42.00 | 9% of (£2,916.67 − £2,448.75), rounded down to whole pounds |
| Net pay in this illustration | £2,255.75 | Gross less pension, PAYE, NI and student loan |
The pension is 5% of (£2,916.67 − £520), rounded to £119.83. HMRC’s Tables A month 1 pay adjustment for code 1257L is £1,048.26: 2 × £416.67 plus £214.92. Subtracting it from £2,796.84 leaves £1,748.58; the manual method rounds this down to £1,748 before applying 20%. The annual Personal Allowance divided by 12 is not the manual code adjustment.
HMRC’s payroll-checking collection links to Tables A and the 2026–27 taxable-pay tables. Our checker provides an annualised estimate; ask payroll to check exact period calculations, especially cumulative pay and tax to date.
Year-to-date figures
Pay to date is a running total, not this month’s salary. Year-to-date (YTD) figures cover the tax year beginning on 6 April. A taxable-pay total can grow each payday even when your monthly pay stays the same. YTD figures are optional payslip information; a missing total does not mean you were not paid.
Continue the illustrative £2,000 gross and £100 net pay pension example above. Assume the same employer pays you at each month end from April, with no other pay, benefits or adjustments. Monthly taxable pay stays at £1,900:
| Payment | Taxable pay this month | Taxable pay to date |
|---|---|---|
| 30 April | £1,900 | £1,900 |
| 31 May | £1,900 | £3,800 |
| 30 June | £1,900 | £5,700 |
| 31 July | £1,900 | £7,600 |
| 31 August | £1,900 | £9,500 |
August’s £9,500 less May’s £3,800 is £5,700: the three £1,900 payments for June, July and August. It is not a £5,700 monthly pay rise. Compare matching columns on consecutive payslips; use the current-period gross, taxable and NI-able figures for a single-payment check.
If a total does not reconcile, ask: “Does this figure cover this employment only, or include earlier pay from my P45? Which payments, pension deductions and corrections explain the change?” Keep the payslips and match corresponding pay and tax fields with your P60. You get a separate P60 for each job held on 5 April. A headline annual salary is not automatically the taxable pay received in that tax year.
Cumulative PAYE also needs tax already deducted, the full tax code and the pay period. Dividing YTD tax by gross pay does not verify it. See cumulative and non-cumulative tax if the basis on your payslip is unclear.
Legal requirements
UK employment law places clear obligations on employers regarding payslips, and knowing these rights empowers you to challenge incorrect or incomplete pay documentation.
Right to a payslip: employees and workers normally have a right to a payslip on or before payday, in print or electronically. GOV.UK lists exceptions, including contractors and freelancers, the police and certain workers at sea.
Pay and deductions: the payslip must show gross pay, net pay and variable deductions such as tax and NI. Fixed deductions must be explained on the payslip or in a separate written statement supplied before the first payslip and updated each year.
Hours-based pay: if any part of your pay is calculated by reference to the number of hours worked, the payslip must state those hours. This applies to hourly-rate workers and those on variable hours.
If information is missing or a deduction is unexplained, start with payroll and follow GOV.UK’s payslip guidance on resolving a problem.
What to do next
- PAYE tax depends heavily on the tax code and tax year.
- NI uses different thresholds from income tax.
- Salary sacrifice reduces cash pay before some deductions, but EV schemes can still create BIK tax.
- Use the checker for an estimate, then ask payroll to explain differences using your code, pay period and pay and tax to date.
- Use the calculator if you want to model changes before the next payslip.
- Check the salary-sacrifice guide if an employer benefit has started.
Try the tool
Check your payslip or model a change.
Use the checker if you already have a payslip. Use the calculator if you want to model take-home pay or salary-sacrifice changes before payday.
About this guide
Written by Dan. Dan has spent 20 years working across payroll, HR, benefits and reward. IsMyPayRight is an independent personal project, not connected with any employer or with HMRC.
AI tools help with research and drafting. The official sources used are listed at the end of the guide.
This is general guidance, not a professional review of your circumstances. Read our editorial process and the corrections log.
Methodology and sources
See how the calculations work, which sources they use, how results are tested, and which payroll details the estimates cannot verify.
Common questions
- Why is taxable pay to date higher when my salary has not changed?
- Pay to date adds up payments in the tax year from 6 April. Five monthly taxable payments of £1,900 total £9,500, while the monthly amount stays £1,900. Compare matching current-period and year-to-date columns, and ask payroll about earlier employment figures or corrections if the totals do not reconcile.
- Which payslip deductions reduce tax before PAYE is worked out?
- Net pay pension contributions reduce taxable pay but not NI-able pay. Pension salary sacrifice generally reduces both. Relief-at-source pension contributions and student loan repayments do not reduce either payroll figure.
- Why are some deductions taken after tax?
- Because they are collected from net pay rather than from taxable pay. Relief-at-source pension contributions, student loans, and many court-ordered deductions appear after PAYE and NI.
- Can two deductions look similar on a payslip but affect tax differently?
- Yes. Net pay and relief-at-source pensions receive tax relief differently, while pension salary sacrifice can also reduce NI. Check the arrangement with payroll rather than relying on the deduction label alone.
- What deductions should be on my payslip?
- Most employees see Income Tax (PAYE) and National Insurance. A workplace pension contribution appears if you are enrolled, and student loan repayments if you have a loan and earn above your plan’s threshold. Others, such as union fees, salary sacrifice or court orders, appear only if they apply to you. Fixed deductions must be explained on the payslip or in a separate written statement.
- What is NI-able pay, and should it match taxable pay?
- NI-able pay is the earnings your National Insurance is worked out on. It does not have to match taxable pay. A net pay pension contribution reduces taxable pay but not NI-able pay, while pension salary sacrifice usually reduces both.
Official sources
Use these references to check the rules behind this guide. Check the tax year and your circumstances before applying an example to your own pay.
- Debt repayments taken from wages
GOV.UK
- Workplace pensions: joining and opting in
GOV.UK
- Rates and thresholds for employers 2026 to 2027
HMRC
- Student and postgraduate loan deduction tables 2026 to 2027
HMRC
- Check your payroll calculations manually
HMRC
- Workplace pension contributions
GOV.UK
- Payslips: employee rights
GOV.UK
- Pension contributions: PAYE and National Insurance treatment
HMRC
- Payslip fields and optional tax-year totals
HMRC
- P60: tax-year dates and separate employment records
HMRC