The payslip atlas
A payslip, explained.
All those boxes, codes and deductions. Pick a numbered line on an example payslip to see what it means, how the figures fit together and what to check on your own.
Fictional examples. Real pay rules. Free to explore.
Example 01
NHS nurse payslip
Band 5 entry · England · April 2026 · Basic pay only
Illustrative NHS ESR-style layout
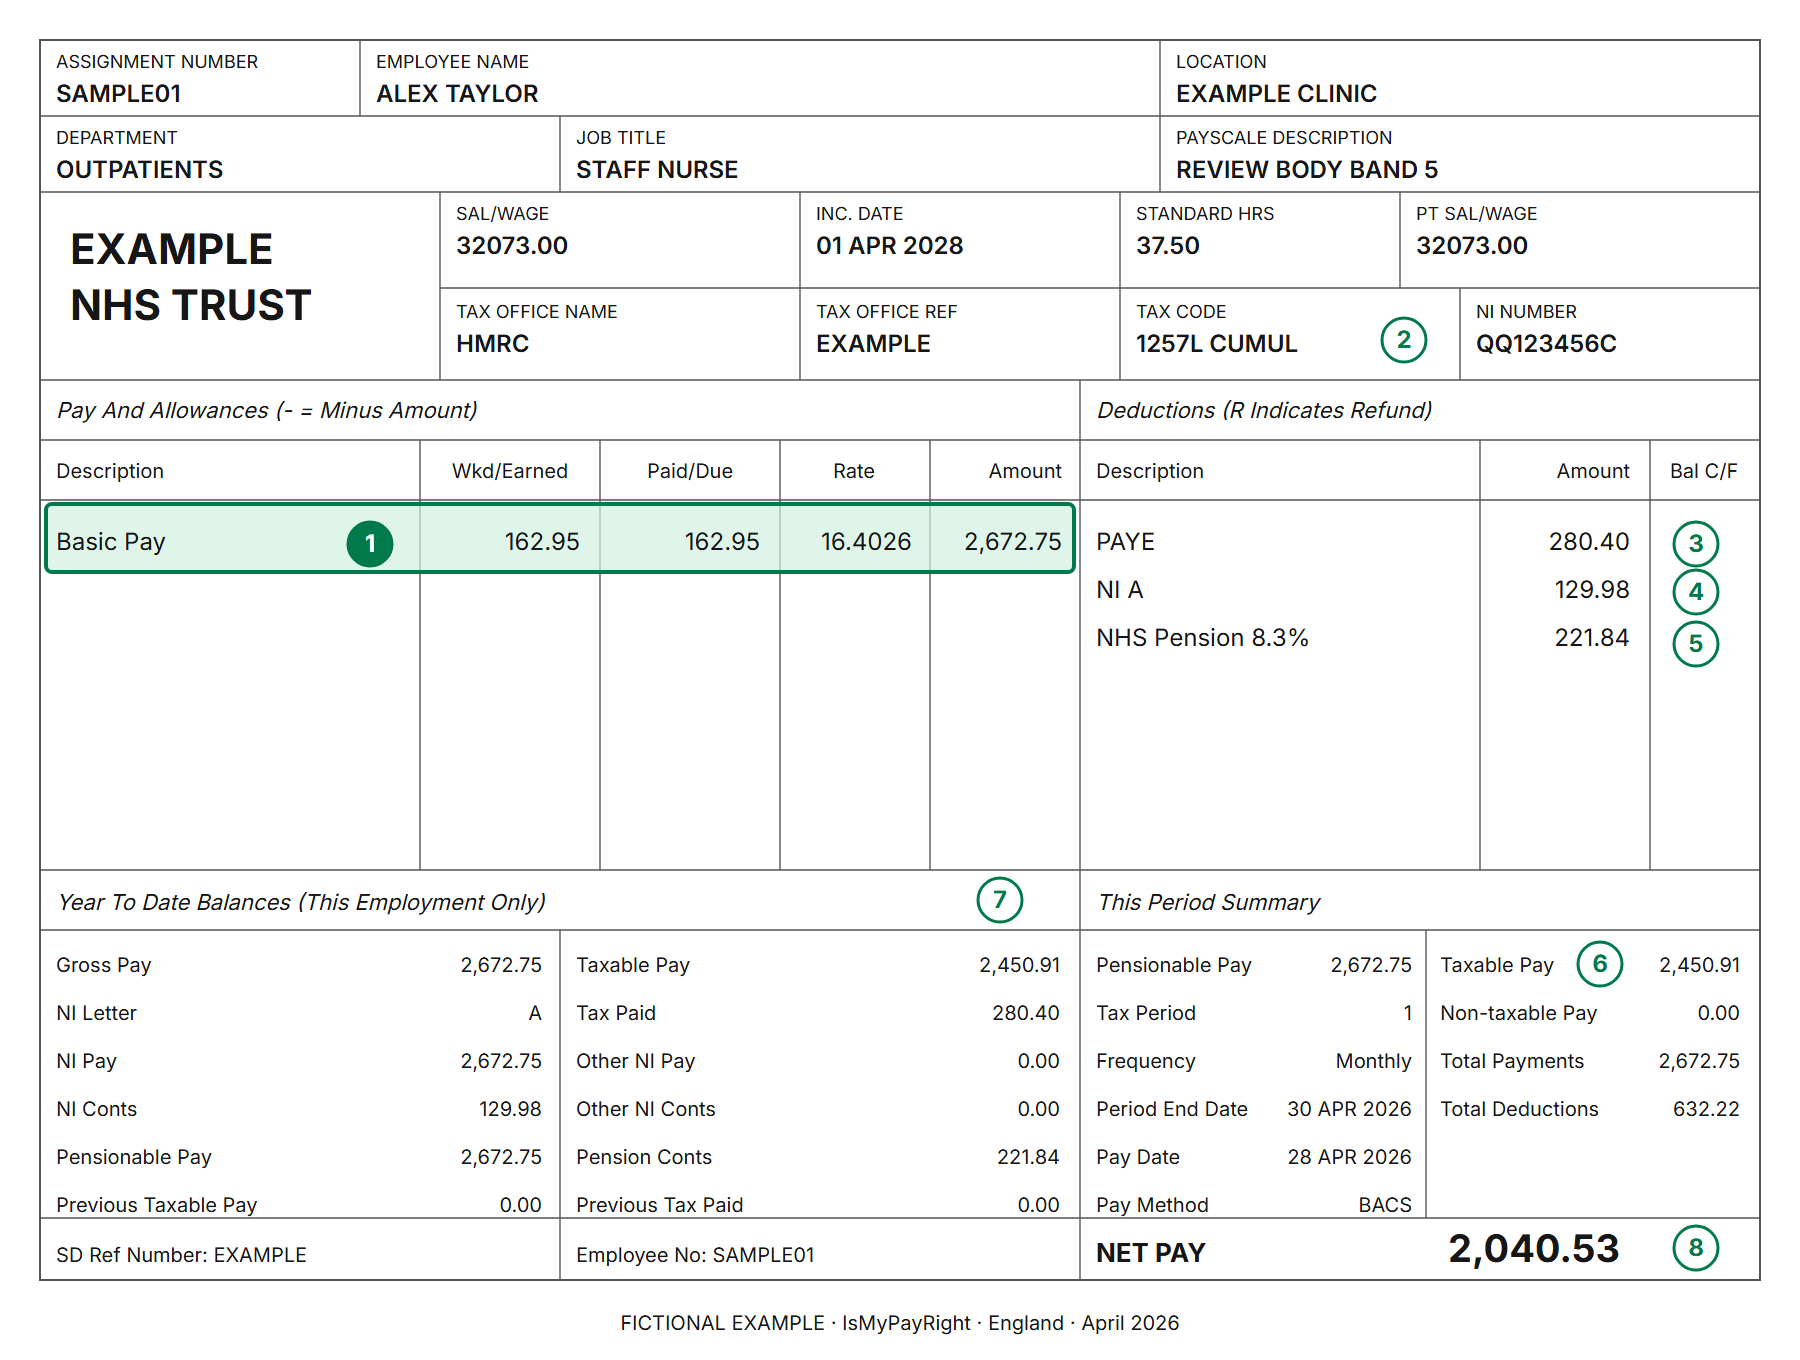
Fictional employee and employer. Based on published NHS ESR guidance; employer layouts can differ. Use the numbered explanation buttons, or enlarge the payslip to select a line on the document.
Line 1 of 8
Basic pay
£2,672.75
Your salary for this pay period, before deductions. Here, £32,073 divided by 12 gives £2,672.75. This nurse has no extra shift payments in this example.
On your own payslip
Match your pay step and contracted hours to your pay letter. Shift enhancements usually have their own lines.
Read all 8 explanations
1. Basic pay
Your salary for this pay period, before deductions. Here, £32,073 divided by 12 gives £2,672.75. This nurse has no extra shift payments in this example.
Match your pay step and contracted hours to your pay letter. Shift enhancements usually have their own lines.
2. Tax code and basis
The code tells payroll how to work out Income Tax. Cumulative means it looks at pay and tax so far this tax year. This is month 1, with no earlier pay or tax to include.
Compare the whole code with your HMRC coding notice, including any S, C, W1 or M1 marker.
3. PAYE Income Tax
Income Tax taken through payroll. In this example, pension contributions reduce the pay subject to tax first. The tax-code allowance and HMRC payroll rounding then give £280.40.
Use taxable pay, the code, tax month and earlier pay and tax together. Gross pay alone cannot establish the right PAYE amount.
4. National Insurance
NI A means employee National Insurance under category A. Here, 8% of monthly earnings above £1,048 gives £129.98 after rounding. The NHS pension contribution does not reduce this earnings figure.
Check your NI category and the earnings used for this period. NI usually works payday by payday, rather than cumulatively like PAYE.
5. NHS pension contribution
The employee pension deduction is 8.3% of £2,672.75 pensionable pay, rounded to £221.84. This NHS pension uses a net pay arrangement: the contribution comes out before Income Tax.
Check pensionable pay and your contribution tier. An employer pension contribution is separate from the amount deducted from your pay.
6. Taxable pay
This is pay subject to Income Tax before the tax-code allowance. Gross pay of £2,672.75 less the £221.84 pension gives £2,450.91. The NI-able and pensionable totals remain £2,672.75 here.
Keep gross, taxable, NI-able and pensionable pay separate. They can be different even on the same payslip.
7. Year-to-date balances
These are running totals for this employment in the tax year starting 6 April. They match the current-period figures here because this is the first payment of the tax year.
Compare like-for-like columns. A growing year-to-date total does not mean that this month’s pay has increased.
8. Net pay
The amount paid into the bank. £2,672.75 gross pay less £280.40 Income Tax, £129.98 NI and £221.84 pension leaves £2,040.53.
Match this amount and the pay date to your bank payment. If they differ, ask payroll to explain the payment or adjustment.
Follow the money
From £2,672.75 to £2,040.53
Employee deductions account for the £632.22 difference. Employer contributions are paid separately and do not come off this take-home amount.
| Item | Amount |
|---|---|
| Gross pay | £2,672.75 |
| PAYE Income Tax | -£280.40 |
| Employee National Insurance | -£129.98 |
| Employee pension | -£221.84 |
| Net pay | £2,040.53 |
The example’s assumptions
- England taxpayer; NHS Agenda for Change in England; Band 5 entry point.
- Full-time, 37.5 hours a week; £32,073 annual basic salary paid in 12 equal instalments.
- April 2026, tax month 1; code 1257L on a cumulative basis; NI category A.
- NHS Pension Scheme employee contribution of 8.3%, deducted before Income Tax.
- No earlier pay or tax in this tax year, student loan, other income or taxable benefits.
- No shift enhancements, London supplement, arrears, salary sacrifice or other deductions.
Sources and arithmetic checked 1 November 2026.
See the calculation method
Monthly basic pay is £32,073 ÷ 12 = £2,672.75. The displayed 162.95 hours and £16.4026 hourly rate are rounded; the salary calculation uses the annual amount. The hours conversion uses 52.143 weeks × 37.5 hours ÷ 12.
Pension: £2,672.75 × 8.3% = £221.83825, rounded to £221.84. This leaves £2,450.91 taxable pay, before applying the tax code.
For 1257L in month 1, HMRC’s tax-code routine gives £1,048.26 free pay: £214.92 for the remaining 257 plus two lots of £416.67. £2,450.91 − £1,048.26 = £1,402.65; rounded down to whole pounds, £1,402 × 20% = £280.40 PAYE.
Employee NI: (£2,672.75 − £1,048) × 8% = £129.98. Gross pay less the £632.22 employee deductions gives £2,040.53.
These are independently worked fictional illustrations using published rules and the stated contract assumptions. Actual payroll can depend on earlier pay, the employer’s settings and rounding method.
Sources for the layout and figures
- Understanding your pay
North Tees and Hartlepool NHS Foundation Trust
ESR sections, field names and abbreviations.
- Understanding your NHS payslip (2022–2023)
Maidstone and Tunbridge Wells NHS Trust
Visual reference for the section layout; historical amounts are not used.
- Pay scales for 2026/27
NHS Employers
Band 5 entry salary in England, effective 1 April 2026.
- Cost of being in the Scheme
NHS Business Services Authority
Employee contribution tiers from 1 April 2026.
- Payroll technical specifications: Income Tax
HMRC
Version 24.0: code allowance, monthly calculation and rounding.
- Rates and thresholds for employers 2026 to 2027
HMRC
Category A monthly NI threshold and employee rate.
- Employer further guide to PAYE and National Insurance contributions
HMRC
Net pay pension contributions reduce PAYE pay, without reducing NI earnings.
- Annualised hours
University Hospitals Birmingham NHS Foundation Trust
52.143-week conversion and equal monthly salary instalments.
Now look at your own payslip
Start with the pay period and gross pay, then follow each deduction through to net pay. Our checker can help you compare the figures and prepare a useful question for payroll.